 Canada
 United States
 Bahamas
 Jamaica
 Trinidad & Tobago
 Antigua & Barbuda
 Barbados
 Anguilla
HR and Payroll in Canada: ROE Errors and Severance Gaps
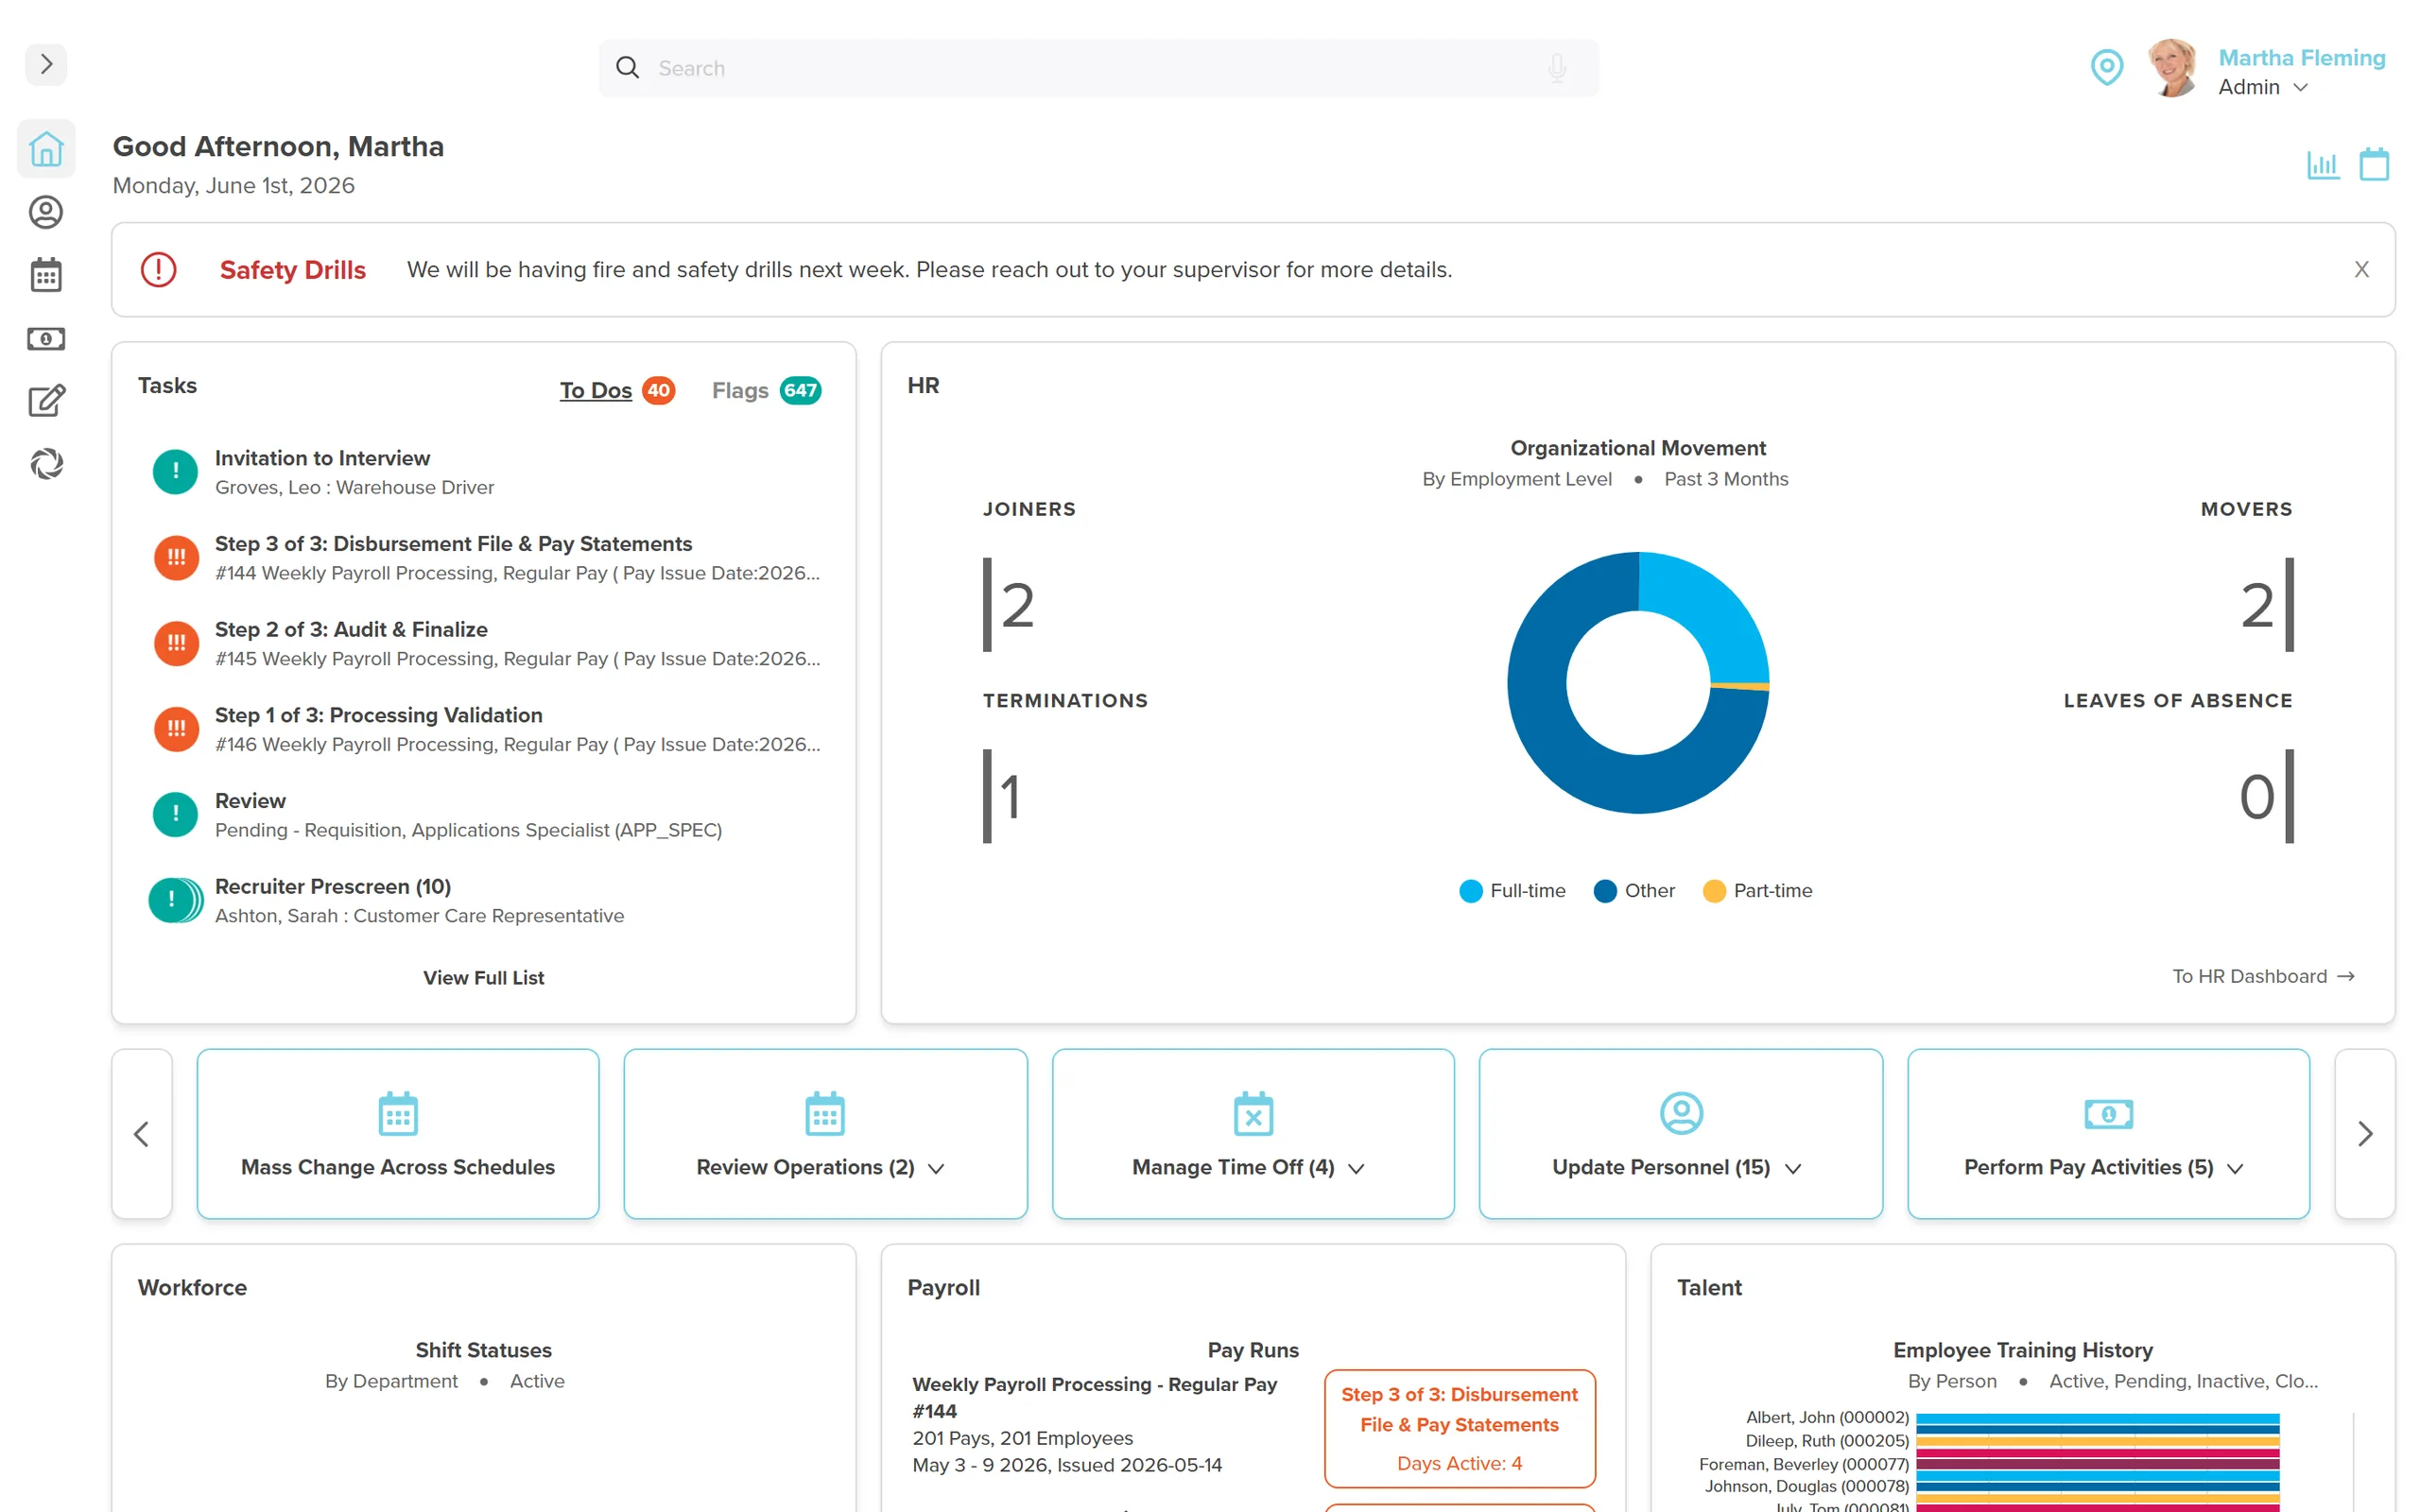
Most Canadian employers don't rack up payroll penalties because they cut corners. They rack them up because they ran one province's rules in another province's payroll. It's the pattern we see across our Canadian client base again and again: a company hires across Ontario, Alberta, and B.C., the payroll lead applies the rules they already know, and the penalty letters start arriving a few months later. Different provinces. Different tax rates. Different employer health taxes. Same letter from the CRA.
This is the reality of running HR and payroll in Canada. The federal framework gives you structure, but the provincial layer adds complexity that catches even experienced teams. Ten provinces, three territories, each with its own employment standards legislation, its own statutory holidays, its own leave entitlements, and its own payroll obligations on top of the federal ones.
HR and payroll in Canada requires employers to navigate a dual federal-provincial system covering employment standards, mandatory payroll deductions (CPP, CPP2, EI, income tax), statutory filings (T4s, ROEs, remittances), provincial leave and holiday entitlements, pay equity obligations, and workforce management requirements that vary by jurisdiction. Getting any layer wrong triggers penalties from the CRA, provincial labour boards, or both.
This guide pulls together everything a Canadian employer needs to know, from the deduction math to the compliance calendar to the provincial differences that trip people up. If you've read our individual guides on specific topics, this is the map that shows how they all connect.
- Canadian employers must withhold CPP (5.95%), CPP2 (4% on earnings between $74,600 and $85,000), EI (1.63% employee, a multiple of that employer-side), plus federal and provincial income tax on every pay run
- A Canadian employer can owe employment standards across every jurisdiction where it has staff: one federal framework plus each relevant province or territory, each with its own rules
- Provincial employment standards govern minimum wage, overtime, statutory holidays, and leave entitlements, and they differ significantly across jurisdictions
- T4 due last day of February following the year; on time if received or postmarked by the next business day when that date is a weekend or CRA holiday; ROE due within 5 or 15 calendar days depending on pay-period type; paper filing timed differently
- Pay equity legislation is now active federally and in Ontario, Quebec, and other provinces with different reporting requirements
The Federal-Provincial Split: Why HR and Payroll in Canada Is Uniquely Complex
Canada doesn't have one set of employment rules. It has fourteen. The federal government sets the framework for payroll deductions, pensions, and employment insurance. But employment standards, the rules governing how you actually manage people, are provincial.
That means minimum wage, overtime thresholds, vacation entitlements, statutory holidays, termination notice, and severance obligations all depend on which province your employee works in. Not where your head office sits. Not where the employee lives. Where they physically (or primarily) work.
For a company with employees in Ontario, Alberta, and B.C., you're running three different sets of employment standards, three different statutory holiday calendars, and three different leave entitlement structures. On top of one set of federal payroll deductions that themselves change every January. That's not a discipline problem. That's a jurisdiction problem, and no amount of care makes one province's rules work in another.
Payroll Deductions: The Numbers That Change Every January
Every Canadian employer must withhold three categories of deductions from every employee paycheque: CPP contributions, EI premiums, and federal/provincial income tax. The rates and ceilings change annually, and missing an update is one of the most common sources of CRA penalties.
Canada Pension Plan (CPP and CPP2)
CPP contributions run from age 18 to 70; stopping is optional starting at 65, on earnings above the basic exemption; confirm the current exemption amount on the CRA's CPP contribution rates and maximums page. For 2026:
- First ceiling: $74,600 at 5.95% (employee and employer each)
- Second ceiling (CPP2): $85,000 at 4% on earnings between $74,600 and $85,000
- Maximum annual employer cost per employee: $4,646.45 (CPP + CPP2 combined)
CPP2 is now in its third year and it's the deduction most likely to be misconfigured. It's not a rate increase on regular CPP. It's a separate calculation on a separate earnings band. Systems that treat it as one blended rate will under-deduct for employees earning between the two ceilings.
Quebec employees contribute to the Quebec Pension Plan (QPP) instead, at a higher rate of 6.30%. If you have staff in Quebec, this requires a completely separate calculation path. We've covered the full deduction math, including the 2026 rate changes, in our Canadian payroll deductions guide.
Employment Insurance (EI)
EI premiums apply to almost every employee in insurable employment:
- Employee rate: 1.63% (1.30% in Quebec due to QPIP)
- Employer rate: a multiple of the employee rate, up to $1,572.30 per employee for 2026
- Maximum insurable earnings: $68,900
The employer always pays more than the employee on EI. That multiplier is baked into the formula. And if you have employees in Quebec, the reduced EI rate is offset by QPIP (Quebec Parental Insurance Plan) contributions, which add another calculation layer.
Federal and Provincial Income Tax
The lowest federal income-tax rate changed during 2025 and applies for the full 2026 year, and provincial rates and brackets vary widely by province, each with its own surtaxes and basic personal amounts. The province of employment determines which provincial rate applies. Confirm the current federal and provincial rates and brackets on the CRA's payroll deductions and contributions page before configuring withholding.
For remote employees, determine province of employment under CRA's employer-establishment and reasonable-attachment rules. A home address alone does not decide withholding.
Before provincial add-ons such as workers' compensation premiums or an employer health tax, the mandatory employer-side ceiling per employee is the CPP/CPP2 employer match, $4,646.45, plus an EI employer premium of up to $1,572.30, on top of salary. These figures are non-negotiable and increase every year with rate adjustments.
CRA Remittances: Deadlines That Shift as You Grow
Withholding the right amounts is only half the job. Remitting them to the CRA on time is where many growing companies stumble. Your remittance frequency depends on your average monthly withholding amount (AMWA), using CRA’s reference-year and notification rules. Check the account’s assigned category instead of inferring an immediate change from current payroll size. The AMWA bands and their due dates change from time to time; confirm the current thresholds and deadlines on the CRA's remitter types page rather than budgeting around a number printed here.
The CRA charges a penalty when payroll source deductions of more than $500 are remitted late or are not remitted at all: 3% if the amount is 1 to 3 days late, 5% if it is 4 or 5 days late, 7% if it is 6 or 7 days late, and 10% if it is more than 7 days late or if no amount is remitted. Amounts under $500 draw the penalty only where the failure was made knowingly or under circumstances of gross negligence. The rate rises to 20% the second or subsequent time the penalty is assessed in a calendar year, where the failures were made knowingly or under circumstances of gross negligence. Each late remittance draws its own penalty under this schedule; there is no annual cap that limits repeated exposure.
We've written a detailed breakdown of remittance rules, including what triggers a frequency change and how to avoid the most common timing mistakes, in our CRA remittance guide.
Year-End Filing: T4s and the February Deadline
Apply CRA’s T4 reporting conditions to each employee, including former staff. Quebec employers also need RL-1 slips. T4 slips and the T4 Summary are due by the last day of February following the calendar year the information return applies to. When that due date falls on a Saturday, a Sunday, or a public holiday recognized by the CRA, the return is considered on time if the CRA receives it, or it is postmarked, on or before the next business day. Every T4 must reconcile with your actual remittances for the year.
Common T4 errors that trigger CRA reviews include missing taxable benefits (company cars, group insurance premiums), CPP pensionable earnings that don't match insurable earnings calculations, and incorrect province of employment codes.
Our T4 slip guide covers the full process, from generating accurate slips to handling amendments and avoiding the reconciliation errors that attract CRA attention.
Records of Employment: The Filing Nobody Gets Right
An interruption of earnings occurs when an employee has had or is anticipated to have 7 consecutive calendar days with no work and no insurable earnings from the employer. It also occurs when an employee's salary falls below 60% of their regular weekly earnings and the separation is due to illness, injury or quarantine, pregnancy, parental leave, or providing care or support to a critically ill or injured family member, and whenever an employee starts receiving wage loss insurance payments. An employer filing a Record of Employment electronically on a weekly, biweekly or semi-monthly payroll must issue it within 5 calendar days after the end of the pay period in which the employee's interruption of earnings occurs. On a monthly payroll, or a payroll with 13 pay periods a year, the deadline is the earlier of 5 calendar days after the end of that pay period or 15 calendar days after the first day of the interruption of earnings. An employer issuing a paper Record of Employment must issue it within 5 calendar days of the first day of the interruption of earnings, or of the day the employer becomes aware of the interruption, whichever applies.
The ROE reason code supports Service Canada's EI administration. Use the actual circumstances and Service Canada guidance.
Block 15A reports total insurable hours, 15B total insurable earnings, 15C earnings by pay period, and Block 17 separation payments. Our ROE guide walks through every block and the mistakes that generate Service Canada inquiries.
Provincial Employment Standards: Where the Real Differences Live
Federal payroll deductions are the same across the country. Employment standards are not. Here's where the provincial split creates the most complexity for multi-province employers.
Minimum Wage
Minimum wage differs by province, changes at different times of the year depending on the province, and some rates are indexed to inflation while others require legislative action to increase. Confirm the current rate for each province where you employ staff on the Government of Canada's minimum wage database rather than budgeting around a number printed here.
For employers with hourly staff across provinces, this means different base pay calculations by jurisdiction, and different overtime thresholds since overtime is typically calculated as a multiple of the applicable minimum or regular rate.
Overtime Rules
Overtime eligibility and rates vary significantly:
- Ontario: 1.5x pay after 44 hours/week for most employees, weekly unless a contract or collective agreement or averaging agreement says otherwise, managers/supervisors excluded
- Alberta: overtime after 8 hours/day or 44 hours/week, whichever is greater, at 1.5x, unless the employer and employee have an overtime agreement providing time off instead
- B.C.: 1.5x after 8 hours/day or 40 hours/week (only first 8 hours/day count toward the weekly total), double time after 12 hours/day; averaging agreements and managers excluded
- Quebec: standard work week 40 hours; overtime premium 50% (1.5x) of the hourly wage; managers, uncontrollable-hours and farm workers excluded; paid time off may substitute, taken within 12 months
- Saskatchewan: Saskatchewan overtime: after 8 hours a day or 40 hours a week, at 1.5 times the hourly wage
- Manitoba: Manitoba overtime: after 8 hours a day or 40 hours a week, at 1.5 times the regular wage
B.C.'s daily double-time provision catches employers who are used to Ontario's simpler weekly-only calculation. Saskatchewan also sets its own vacation floor: Saskatchewan vacation: 3 weeks a year, rising to 4 weeks after 10 years with the same employer. Every other province and territory not listed sets its own overtime and vacation rules; confirm the current rule directly with the relevant employment standards office before running payroll on an assumed threshold.
Statutory Holidays
The number of statutory holidays varies by province, and the eligibility rules for holiday pay differ by jurisdiction too. Ontario recognizes nine public holidays under the Employment Standards Act: New Year's Day, Family Day, Good Friday, Victoria Day, Canada Day, Labour Day, Thanksgiving Day, Christmas Day, and Boxing Day. Our statutory holiday pay guide covers the calculations province by province, including the averaging formulas that most employers apply incorrectly; confirm any other province's current count directly with that province's employment standards office before relying on it.
| Province | Overtime Threshold | Min. Vacation (first qualifying year) |
|---|---|---|
| Ontario | 44 hours | 2 weeks (4 percent) |
| Alberta | 8 hours/day or 44 hours/week | 2 weeks (4%) |
| B.C. | 8 hours (1.5 times), 12 hours (2x) | 2 weeks (4%) |
| Quebec | 40 hours/week | 2 weeks (4%) |
Saskatchewan's overtime and vacation rules, and Manitoba's overtime rule, are above. Manitoba's vacation entitlement, and every other province and territory's overtime and vacation rules beyond what's covered above, have not yet cleared this page's primary-source check. Confirm the current rule directly with the relevant provincial or territorial employment standards office, such as Manitoba's, before applying one rate to everyone.
Leave Entitlements: More Than Just Vacation
Beyond vacation, Canadian employers must navigate a growing list of protected leaves, and the entitlements differ by province.
Parental and Maternity Leave
EI: 15 weeks maternity; parental 40 weeks standard (35 max to a single parent) or 69 weeks extended (61 max to a single parent), on Service Canada's own benefit-week schedule, separate from the province's job-protected leave period. In Ontario, Ontario: 13-week qualifying employment for either leave; 17 weeks pregnancy leave (may be longer); parental leave 61 weeks (after pregnancy leave) or 63 weeks (otherwise). In B.C., BC: 17 weeks maternity leave; parental leave 61 weeks (after maternity leave) or 62 weeks (otherwise, or adopting). Every other province sets its own job-protected leave length; confirm it directly with that province's employment standards office before relying on a number for a jurisdiction not named here.
Our parental leave guide breaks down the interaction between federal EI benefits and provincial job protection, including the top-up policies that competitive employers are increasingly offering.
Sick Leave and Personal Emergency Leave
Post-pandemic, most provinces expanded their unpaid sick leave entitlements. Under Ontario's Employment Standards Act, an employee who has been employed for at least two consecutive weeks is entitled to up to three days of unpaid, job-protected leave each calendar year because of a personal illness, injury, or medical emergency. Under the British Columbia Employment Standards Act, an employee who has been employed for at least 90 consecutive days is entitled, in each calendar year, to paid leave for the number of days prescribed by regulation and to up to 3 days of unpaid leave for personal illness or injury. The Employment Standards Regulation prescribes 5 days of paid leave. Federally regulated employees get their own entitlement, and it's paid, not unpaid: Federal paid medical leave accrues to a maximum of 10 days a year. These differences create compliance headaches for employers operating across provincial borders.
Severance and Termination: The Expensive Compliance Gap
Termination obligations in Canada combine statutory minimums with common law entitlements, and the gap between the two is where most wrongful dismissal claims originate.
1 to 8 weeks of Ontario termination pay for individual terminations, banded by years of service Under Ontario's Employment Standards Act, an employee whose employment is severed after five or more years of service is entitled to severance pay equal to regular wages for a regular work week multiplied by the sum of completed years of employment plus completed months divided by 12 for a year that is not completed, to a maximum of 26 weeks, if the employer has a global payroll of at least $2.5 million or severed 50 or more employees in a six-month period because all or part of the business permanently closed. Severance pay is separate from and additional to termination pay.
Courts can and regularly do award common law reasonable notice that exceeds the statutory minimum for long-tenure employees, but there is no fixed formula; it is decided case by case on the Bardal factors, not a multiple of years served. The total liability surprises employers who only planned for the statutory minimum.
Our severance pay guide covers the statutory formulas by province and the Bardal factors courts use to determine common law notice periods.
Canadian payroll compliance, handled
Workzoom calculates CPP, CPP2, EI, and federal/provincial tax across every Canadian jurisdiction. Statutory holiday pay, leave tracking, termination calculations, T4 generation, ROE filing. One system, $4/employee/month, no implementation fees, month-to-month.
Book a 30-Minute WalkthroughPay Equity: The Compliance Requirement That's Expanding
Pay equity legislation is no longer limited to the public sector. A federal Pay Equity Act now covers federally regulated employers above a headcount threshold; confirm the current threshold on the Department of Justice's Pay Equity Act text. Under Ontario's Pay Equity Act, an employer covered by the Act, meaning every public-sector employer and every private-sector employer with ten or more employees, must establish and maintain compensation practices that provide for pay equity in every establishment of the employer. Quebec has also had its own proactive pay equity regime in force for years; confirm the current requirements with CNESST.
The pattern is clear: provinces are moving toward proactive pay equity (employer must audit and fix gaps) rather than complaint-based models (employee must file a grievance). Employers who wait for a complaint to trigger action are operating on a model that's being legislated out of existence.
We've covered the current landscape, including the reporting timelines and the penalties for non-compliance, in our pay equity legislation guide.
Workforce Management: Time Tracking, Scheduling, and Compliance
Everything discussed so far, overtime, statutory holidays, leave entitlements, depends on accurate time and attendance data. If you don't know exactly how many hours each employee worked, in which jurisdiction, on which days, your payroll calculations are built on estimates.
Our time tracking guide covers the compliance implications of different tracking methods and why integrated time-to-payroll systems eliminate the data re-entry errors that cause most deduction mistakes.
The connection between HR and payroll isn't optional in Canada. When an employee changes provinces, goes on leave, gets promoted, or has a change in benefits, that information must flow into payroll calculations immediately. Any gap between the HR record and the payroll record is a compliance gap waiting to surface. And if you've been holding fourteen jurisdictions together by hand, you're not the problem. The work of keeping every provincial rule synced to one payroll by memory is, and that is exactly the work a system should carry for you.
The Canadian Software Question
Canadian payroll has rules that non-Canadian software vendors routinely get wrong. CPP2's second ceiling. Quebec's parallel deduction system (QPP, QPIP, provincial parental insurance). Provincial employer health taxes. The T4/RL-1 filing requirements. ROE generation with correct insurable earnings calculations.
Our best HR software for Canada guide evaluates platforms specifically on their ability to handle these Canadian requirements natively, not through workarounds or manual overrides.
For employers specifically looking for payroll software built in Canada, for Canadians, our Buy Canadian guide covers why data residency, provincial compliance depth, and CRA integration matter more than feature lists.
HR Compliance: The Annual Checklist
Canadian HR compliance isn't a one-time setup. It's an annual cycle with deadlines, rate changes, and legislative updates that require active management. Our HR compliance checklist for 2026 consolidates every deadline and obligation into a single actionable reference.
Key annual milestones include:
- January: Update all payroll deduction rates (CPP, CPP2, EI, tax brackets, provincial minimums)
- February: File T4s and RL-1s by month-end
- March: Review pay equity obligations and reporting deadlines
- April: Workers' compensation annual reporting (varies by province)
- Throughout: Track provincial employment standards changes, minimum wage increases, and new leave entitlements as they take effect
Industry-Specific Considerations
Certain Canadian industries face additional HR and payroll complexity beyond the standard framework.
Seasonal and hospitality employers deal with fluctuating headcounts, ROE generation for seasonal layoffs, and overtime calculations during peak periods. Our ski resort HRIS guide covers the specific challenges of managing seasonal workforces in Canada.
Healthcare, construction, and municipalities often have union collective agreements that override or supplement provincial employment standards, adding another layer of rules on top of the statutory framework.
Multi-jurisdiction employers with employees in both Canada, the US, and the Caribbean face an entirely different set of challenges. The payroll deduction structure in Jamaica or the Bahamas bears almost no resemblance to the Canadian system, and running both through one platform that handles each natively is the only way to avoid parallel manual processes.
Canadian HR and payroll compliance is not a single system. It is fourteen overlapping systems: one federal framework for deductions and pensions, and thirteen provincial/territorial frameworks for employment standards. The employers who stay compliant are the ones whose systems encode these rules natively, rather than relying on someone remembering which province uses which overtime formula.
What's Changing in 2026 and Beyond
Several significant changes are either already in effect or on the horizon for Canadian employers:
- The federal lowest tax bracket changed in the 2026 federal budget. Payroll systems that didn't update their tax tables in January are withholding against a stale bracket; confirm the current rate on the CRA's payroll deductions page linked above.
- CPP2's second ceiling continues to rise year over year and will increase further in 2027. See the payroll deductions section above for the current ceiling.
- Pay equity reporting deadlines are approaching for federally regulated employers who established their plans in the prior cycle.
- Provincial sick leave entitlements continue to expand. up to 3 unpaid sick days per year after 90 days of employment, plus the paid days the Employment Standards Regulation prescribes (currently 5) may become the model other provinces follow.
- Right-to-disconnect legislation is gaining traction beyond Ontario, with several provinces considering similar requirements for employers above certain headcount thresholds.
The pattern in Canadian employment law is consistent: obligations expand, reporting requirements increase, and penalties for non-compliance get steeper. The employers who invest in compliance infrastructure now, systems that automatically update rates, track provincial differences, and generate required filings, are the ones who absorb these changes without scrambling.
For a hypothetical employer running multi-province payroll on a single province's rules: the fix is moving onto a single payroll platform that handles provincial differences natively, before a CRA compliance letter makes the case instead.
One platform for every Canadian jurisdiction
Workzoom handles HR, payroll, workforce management, and talent across every province and territory. CPP, CPP2, EI, provincial tax, statutory holidays, leave tracking, T4s, ROEs. Built in Canada, for Canadian employers. $4/employee/month, no implementation fees, month-to-month.
See Workzoom for Your Team- When to file information returns claim checked Sep 4, 2026
- Employers: How to complete the record of employment (ROE) form claim checked Sep 4, 2026
- Starting and stopping CPP deductions claim checked Sep 4, 2026
- Late remitting/Failure to remit claim checked Sep 4, 2026
- Employers: How to complete the record of employment (ROE) form claim checked Sep 4, 2026
- Your guide to the Employment Standards Act: Overtime pay claim checked Sep 4, 2026
- Employment Standards Code, RSA 2000, c E-9, ss 21, 22 and 23 claim checked Sep 4, 2026
- Employment Standards Act, RSBC 1996, c 113, ss 35 and 40, and Employment Standards Regulation, BC Reg 396/95, s 34 (f) claim checked Sep 4, 2026 also Employment Standards Regulation, BC Reg 396/95, s 34 (f)
- Loi sur les normes du travail, RLRQ c N-1.1, arts 52, 54 et 55 claim checked Sep 4, 2026
- Overtime in a Day Versus Overtime in a Week claim checked Sep 4, 2026 also General Overtime Information
- Employment Standards -- Overtime claim checked Sep 4, 2026
- Annual Vacation and Vacation Pay claim checked Sep 4, 2026
- Your guide to the Employment Standards Act: Public holidays claim checked Sep 4, 2026
- Your guide to the Employment Standards Act: Vacation claim checked Sep 4, 2026
- Employment Standards Code, RSA 2000, c E-9, s 34 claim checked Sep 4, 2026
- Employment Standards Code, RSA 2000, c E-9, s 34.2 claim checked Sep 4, 2026
- Employment Standards Act, RSBC 1996, c 113, ss 57 and 58 claim checked Sep 4, 2026
- Loi sur les normes du travail, RLRQ c N-1.1, arts 67 a 74 claim checked Sep 4, 2026
- EI maternity and parental benefits claim checked Sep 4, 2026
- Your guide to the Employment Standards Act: Pregnancy and parental leave claim checked Sep 4, 2026 also Your guide to the Employment Standards Act: Pregnancy and parental leave -- Qualifying for parental leave
- Employment Standards Act, RSBC 1996, c 113 -- ss 50, 51 claim checked Sep 4, 2026
- Your guide to the Employment Standards Act: Sick leave claim checked Sep 4, 2026
- Employment Standards Regulation, BC Reg 396/95, s 45.031 (prescribed paid-day count for Employment Standards Act, RSBC 1996, c 113, s 49.1) claim checked Sep 4, 2026
- Canada Labour Code, RSC 1985, c L-2, s 239 claim checked Sep 4, 2026
- Your guide to the Employment Standards Act: Termination of employment claim checked Sep 4, 2026
- Your guide to the Employment Standards Act: Severance pay claim checked Sep 4, 2026
- Pay Equity Act, RSO 1990, c P.7, s. 7(1) claim checked Sep 4, 2026
See Workzoom in 30 minutes.
Real product, real questions, no slides. Starts at $4 per employee per month, CAD or USD, with $0 setup fees.
What readers ask after this post on HR and payroll Canada.
Our clients
The teams that run their people on Workzoom.
Workzoom handles HR, payroll, workforce, and talent on one employee record. Book a 30-minute walkthrough.