 Canada
 United States
 Bahamas
 Jamaica
 Trinidad & Tobago
 Antigua & Barbuda
 Barbados
 Anguilla
Payroll Remittance 2026: PD7A Is the CRA's Report Card
Last spring, on a discovery call, an operator told us the same story we hear again and again. Picture a hypothetical growing employer, a single day late on one payroll remittance to the CRA. One day. The penalty ran past a thousand dollars on a mid-size run. Most operators don't expect a one-day slip to cost that much.
Payroll remittance to the CRA is the process of sending withheld CPP contributions, EI premiums, and income tax to the Canada Revenue Agency on a set schedule. Your remitter type determines your deadlines, and the CRA's penalty structure applies from the first day late. See the remitter types section below for the current bands and deadlines, and the penalty structure section for the current schedule.
The penalties are not proportional. They're punitive. And they hit small businesses hardest, because a growing company doesn't have a dedicated compliance team watching the calendar. They have a payroll person who also does benefits, onboarding, and half the HR admin.
What You're Actually Remitting (and Why It's Three Things, Not One)
Every payroll remittance to the CRA bundles three separate obligations into a single payment. People talk about it like it's one thing. It's not.
Canada Pension Plan contributions. You withhold the employee's share of CPP and CPP2, then match it dollar for dollar. For 2026, that's up to $4,230.45 in regular CPP plus $416.00 in CPP2 per employee, and you're paying the same amount on top. Quebec QPP/QPP2 contributions go to Revenu Quebec, along with QPIP and Quebec income tax. Federal income tax and Quebec-rate EI still go to CRA.
Employment Insurance premiums. The employee pays their share (1.63% of insurable earnings, max $1,123.07), and you pay a multiple of that. Your employer EI cost can run up to $1,572.30 per employee for 2026. Quebec employees pay a reduced EI rate because QPIP covers parental benefits separately.
Income tax withheld. Federal plus provincial income tax other than Quebec income tax, based on the employee’s source-deduction forms and province of employment. Quebec income tax is remitted separately to Revenu Quebec. This is typically the largest portion of your remittance. For a deeper breakdown of all the rates and thresholds, see our complete guide to Canadian payroll deductions for 2026.
All three get bundled into a single payment, a single cheque or a single electronic transfer. But the CRA tracks each component separately, and your year-end T4 filing needs to reconcile against every dollar.
The Remitter Types (and How the CRA Decides Yours)
The CRA doesn't let you pick your remittance schedule. It assigns a remitter type using its AMWA reference-year rules. The exact AMWA bands and deadlines can change; confirm the current figures directly on the CRA's remitter types page before building a calendar around what's below.
Here's the shape of it, low AMWA to high:
Quarterly Remitter
Quarterly remitters: new employers under $1,000/month, or existing employers with AMWA under $3,000, both with perfect compliance. This is mostly very small employers. If you're reading a guide this detailed, you've probably graduated past quarterly.
Regular Remitter
Regular remitters: AMWA under $25,000, remit monthly, due the 15th of the next month.
Simple enough, until the due date falls on a weekend or holiday, which happens several times a year. When that happens, the deadline extends to the next business day. But "I thought the date fell on a weekday" is not a defence the CRA entertains.
Accelerated Remitter, Threshold 1
Threshold 1 accelerated remitters: AMWA $25,000 to $99,999.99, remit twice monthly on the 25th and the 10th.
This is the threshold that catches growing companies off guard. CRA generally uses AMWA from the second preceding calendar year to assign accelerated status, with specific rules for eligible category changes. Read the account’s CRA notification and reference-year rules rather than assuming a single hiring quarter changes the schedule immediately.
Accelerated Remitter, Threshold 2
Threshold 2 accelerated remitters: AMWA $100,000 or more, remit up to four times monthly, each due the 3rd working day after the period.
Threshold 2 uses four periods each month ending on the 7th, 14th, 21st, and the last day of the month. It is not simply a remittance within a fixed number of days after each payday. Confirm the applicable due date with CRA before building the calendar.
The Penalty Structure Is Genuinely Punitive
I'm going to be direct about this. The CRA's late remittance penalties are designed to hurt.
Here's the schedule, per the CRA's own penalty guidelines:
The CRA charges a penalty when payroll source deductions of more than $500 are remitted late or are not remitted at all: 3% if the amount is 1 to 3 days late, 5% if it is 4 or 5 days late, 7% if it is 6 or 7 days late, and 10% if it is more than 7 days late or if no amount is remitted. Amounts under $500 draw the penalty only where the failure was made knowingly or under circumstances of gross negligence. The rate rises to 20% the second or subsequent time the penalty is assessed in a calendar year, where the failures were made knowingly or under circumstances of gross negligence. Plus compound daily interest at the CRA's prescribed rate on top of the penalty amount.
Let's do the math on a hypothetical scenario. A hypothetical regular remitter owes a mid five-figure amount for the month and is a few days late. Applying the tiers above, the penalty is a few percent of that amount. The 20% rate is not an automatic add-on: it applies only to a qualifying second or subsequent assessment where failures were knowing or grossly negligent. The mechanics matter more than any one dollar figure.
For what? Being a few days behind on a payment you were already going to make.
The CRA treats a five-day-late remittance from a small manufacturer the same as it treats one from a multinational. The percentage doesn't scale. The dollar amount does.
And here's what really gets under my skin. There's no grace period. No courtesy call. No "hey, we noticed you're a day late, please submit by Friday." The penalty is automatic. The interest starts accruing the day after the deadline. By the time you get the notice, you already owe it.
If your payroll system isn't flagging these deadlines automatically, you're relying on someone's calendar reminder. That works until it doesn't.
How to Actually Make the Payment
You know the balance owing. You know when it's due. Now, how do you get the money to the CRA? There are three methods, and they each have quirks.
My Business Account (CRA Online Portal)
Log into your CRA My Business Account, navigate to payroll, and submit your remittance electronically. You'll need your payroll account number (your business number with the RP extension). The payment processes same-day if submitted before the cutoff, but give yourself a buffer. Submitting minutes before midnight on the due date is a gamble nobody should take.
Online Banking (Pre-Authorized Debit or Bill Payment)
Most Canadian banks let you set up the CRA as a payee. You enter your payroll account number, the payment amount, and submit. Processing time varies by institution, typically a business day or two. This means a payment submitted the day before a deadline through online banking might not clear until after it. The CRA counts the date they receive it, not the date you sent it.
That detail has cost more employers more penalties than I can count.
At a Canadian Financial Institution
You can walk into a bank with a completed PD7A remittance form and make the payment in person. This method gives you a receipt with a timestamp, which is useful if there's ever a dispute about timing. It's also the slowest and most inconvenient method, which is why most companies have moved away from it.
Remittance deadlines shouldn't keep you up at night
Workzoom calculates CPP, EI, and income tax automatically and tracks your remittance schedule so nothing slips. $4/employee/month, no setup fees, no contracts.
See How It WorksYour PD7A: The CRA's Report Card on Payroll Remittance
The CRA issues PD7A statements in forms and frequencies that vary with the account and remitter category. Treat the statement as a reconciliation report: it shows the balance CRA records versus what it has received.
If the numbers do not match, investigate the difference promptly. A statement discrepancy alone does not establish a new interest charge.
Common reasons for PD7A discrepancies:
- Payment was applied to the wrong payroll account number (you might have multiple RP accounts)
- Online banking payment didn't include the correct reference number
- You adjusted an employee's pay retroactively but didn't adjust the remittance
- Taxable benefits were added to T4s at year-end but not remitted during the year
When the PD7A shows a balance owing, reconcile the account promptly and determine whether an amount is actually overdue. Keep the supporting payroll and payment records, then contact CRA business enquiries if correction is needed.
Keep every remittance confirmation number. Every bank receipt. Every My Business Account transaction record. The CRA requires that records, including payroll records, be kept for six years from the end of the last tax year they relate to, unless the CRA has given permission to destroy them earlier. "Our old system didn't save confirmations" won't help.
What the Right System Looks Like
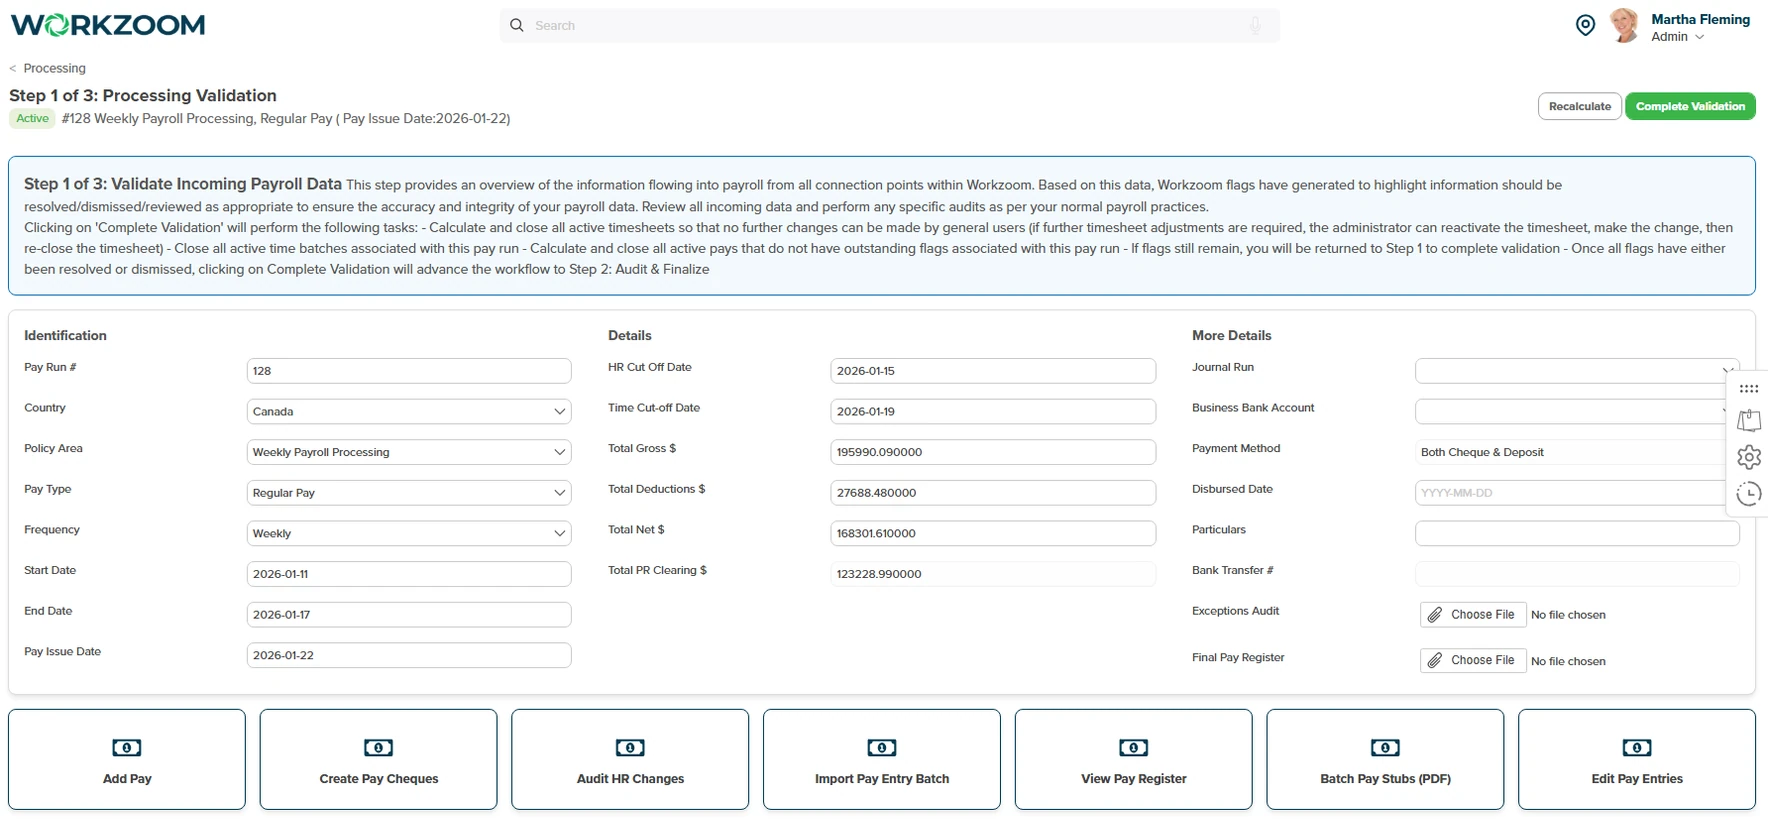
County of Renfrew, an Ontario municipal employer with roughly 900 employees, onboarded 32 new staff in three months without paper-based processing. Their payroll team uses Workzoom to calculate and prepare their remittance submissions. The CRA receives what was calculated correctly. The team submits. No manual reconciliation at quarter-end.
Ktunaxa Nation, with over 200 employees across multiple entities in B.C., runs multi-entity remittances through the same system. Each entity's deductions are calculated separately and prepared for submission. That's not a vague promise about automation. That's calculated deductions, prepared filings, and an employer who clicks submit. It matches the pattern we see across our Canadian client base: the teams that stop missing deadlines are the ones who stop tracking those deadlines by hand.
Year-End Reconciliation: Where Everything Has to Add Up
February is the month that tests every payroll team. T4 slips and the T4 Summary are due by the last day of February following the calendar year the information return applies to. When that due date falls on a Saturday, a Sunday, or a public holiday recognized by the CRA, the return is considered on time if the CRA receives it, or it is postmarked, on or before the next business day. Every number on the T4 information return needs to reconcile with what you remitted throughout the year.
Add employee CPP/CPP2 deductions to the employer match, and employee EI premiums to the applicable employer EI share. Add income tax withheld, then compare that combined liability with remittances credited to the payroll account. Do not add the employer share to amounts already remitted.
If there's a shortfall, the CRA will issue an assessment. If there's an overpayment, you can request a refund, but that process takes weeks. Sometimes months.
The companies that have the smoothest year-ends are the ones whose payroll system handles remittance tracking in real time, not the ones scrambling to reconstruct 12 months of payment records from bank statements in January.
A Calendar You Can Follow
Here's what a regular remitter's year looks like, stripped down to what matters. Confirm the exact monthly due date on the CRA's remitter types page linked above before building this into a calendar:
- Monthly: Remit employee deductions plus employer CPP/CPP2 and EI contributions for amounts paid in the previous month, by the regular remitter's due date
- Quarterly (PD7A review): Compare your records against the CRA's statement of account. Fix discrepancies immediately.
- December payroll: Check taxable benefits and remit by the assigned category’s deadline. A regular remitter’s December amounts are normally due January 15, subject to the business-day rule.
- Year-end: T4/T4A filing deadline, on the date in the year-end filing section above. RL-1 for Quebec employees. Everything reconciles or everything unravels.
For accelerated remitters, the calendar is tighter, with more deadlines per month than a regular remitter and a shorter window on each one. See the remitter types section above for the current cadence at each threshold.
At some point, this stops being a process problem and becomes a systems problem.
If you're manually tracking remittance deadlines on a calendar or spreadsheet, you will eventually miss one. The question isn't if. It's which quarter. Payroll software that auto-calculates remittance amounts and flags due dates is the only reliable safeguard against the CRA's escalating penalty structure.
The Part Nobody Talks About
Here's what frustrates me about payroll remittance in Canada. The system is designed for large employers. Threshold 2 accelerated? Those companies have payroll departments. Plural. They have compliance officers and treasury teams and automated ERP systems that handle remittance as a background process.
But the small manufacturer with 90 people? The nonprofit with 120 staff across three provinces? They're held to the same penalty percentages. The same interest rates. The same documentation requirements.
The CRA doesn't grade on a curve.
So if you're running payroll for a company in that 50 to 500 employee range, this is the compliance risk that deserves your attention. Not because remittance is complicated in theory. It's not. But because the margin for error is exactly zero, and the cost of a single missed deadline is disproportionate to the offence.
And if you have ever missed one, here's the part worth holding onto: you're not the problem. The schedule is unforgiving and the manual process was always going to fail eventually. The fix is the system, not more vigilance from you.
Get the system right. Automate the deadlines. Keep your confirmations. And if your current setup relies on anyone remembering a date, fix that first.
- Types of remitters claim checked Sep 4, 2026 also When to remit (pay)
- Types of remitters claim checked Sep 4, 2026 also When to remit (pay)
- Types of remitters claim checked Sep 4, 2026 also When to remit (pay)
- Types of remitters claim checked Sep 4, 2026 also When to remit (pay)
- Late remitting/Failure to remit claim checked Sep 4, 2026
- Keeping Records claim checked Sep 4, 2026
- When to file information returns claim checked Sep 4, 2026
See Workzoom in 30 minutes.
Real product, real questions, no slides. Starts at $4 per employee per month, CAD or USD, with $0 setup fees.
What readers ask after this post on payroll remittance.
Our clients
The teams that run their people on Workzoom.
Workzoom handles HR, payroll, workforce, and talent on one employee record. Book a 30-minute walkthrough.