 Canada
 United States
 Bahamas
 Jamaica
 Trinidad & Tobago
 Antigua & Barbuda
 Barbados
 Anguilla
CPP and EI Maximum 2026: Every Ceiling and Who Pays What
$416.00 per employee. Matched by you, dollar for dollar. That is what the second CPP ceiling costs in 2026, and most budget spreadsheets do not have a column for it.
Second ceiling, because there are two now. It arrived after most employers had already built the spreadsheet they still use, which is exactly where payroll budgets quietly go wrong.
Workzoom runs Canadian payroll against both 2026 ceilings. The CPP and EI maximum for 2026 is $4,646.45 per employee for CPP, made up of $4,230.45 of base contributions plus $416.00 of CPP2, and $1,123.07 for EI. Employers match CPP exactly and pay 1.4 times the employee EI amount.
Here's the thing about ceilings. They are the easiest numbers in payroll to get right and the most expensive to get wrong, because an error does not show up on one paycheque. It shows up on every paycheque until somebody catches it, and then it shows up again as a year-end adjustment nobody budgeted for.
If your figure is out of date, that is not a failure of attention. The numbers change every November, and any process that depends on a person remembering will eventually meet a November where nobody did. You shouldn't have to reconcile a statutory rate against last year's spreadsheet to find out which one you are running.
What is the CPP maximum for 2026?
An employee who earns above the ceiling contributes $4,646.45 this year. The employer contributes the same amount. That figure is not one calculation. It is two, stacked.
Base CPP runs at 5.95% on the earnings between the $3,500 basic exemption and the first ceiling of $74,600, one line in the Canadian payroll deductions you run every cycle. That leaves $71,100 of contributory earnings, and 5.95% of $71,100 is $4,230.45.
Then CPP2 starts. It runs at 4.00% on the band between $74,600 and $85,000, which is $10,400 wide. Four percent of $10,400 is $416.00. Add the two and you get $4,646.45 from the employee and $4,646.45 from the employer.
The basic exemption applies to the base layer only. It does not reduce the CPP2 band.
What is the EI maximum for 2026?
Employees outside Quebec pay 1.63% on insurable earnings up to $68,900. That caps the employee at $1,123.07.
Employers do not match EI. They pay 1.4 times the employee rate, which puts the employer maximum at $1,572.30 per employee. It is the one place in Canadian payroll where the employer share is larger than the employee share by design, and it is the line finance teams most often model as a straight match.
Put the two programs together and a single maxed-out employee costs an employer $6,218.75 in CPP and EI before any provincial payroll tax, any benefits, and any wages. Those amounts then flow into your CRA remittance schedule, and again into the T4 slips you file the following February.
Why does Quebec come out different?
Two reasons, and they compound.
Quebec employees do not contribute to CPP. They contribute to the Quebec Pension Plan, which is administered separately and carries its own rate schedule. If you are running payroll in Quebec, confirm the current QPP figures with Retraite Québec rather than assuming the federal numbers carry across.
EI is different too. Quebec employees pay 1.30% rather than 1.63%, because the province runs its own parental insurance plan and the federal premium is reduced to reflect it. On the same $68,900 ceiling, that is a maximum of $895.70 instead of $1,123.07.
None of this is exotic. It is two sets of rules in one pay period, the same shape of problem as the rest of the 2026 Canadian payroll rates, and the most common reason a multi-province employer finds a variance in March instead of January.
How does the $3,500 exemption work on a single paycheque?
Not all at once. That is the part people get wrong when they check the math by hand.
The basic exemption is annual, but it is applied in slices across the year rather than absorbed by January. Divide $3,500 by the number of pay periods and each cheque carries its own share. On a biweekly schedule that is $3,500 across 26 periods, roughly $134.61 a period. On semi-monthly it is 24 periods. On weekly it is 52. The Canada Revenue Agency publishes the exact rates, maximums, and per-period figures and the rounding rules that go with them, and those tables govern rather than your own division.
This is why a manual spot check so often disagrees with the payroll system by a few cents. The system is prorating and rounding per period the way CRA specifies. The spreadsheet took the annual number and divided once.
Change an employee's pay frequency mid-year and the arithmetic shifts underneath them. It is a rare change, and it is exactly the kind of rare change that produces a variance nobody can explain in November.
What happens when someone hits the ceiling in August?
The deduction stops. Their net pay goes up, and nothing is wrong.
An employee earning $130,000 clears the $85,000 CPP2 ceiling and the $68,900 EI ceiling well before year end. From the pay period after they cross, the CPP and EI lines disappear from their cheque, and their take-home jumps for the rest of the year. Then it drops again in January when the counters reset.
Two things follow from that, and both are budget items rather than payroll errors.
The employer contribution stops at the same moment, so employer cost per senior employee is front-loaded into the first two thirds of the year. A monthly forecast that spreads CPP and EI evenly across twelve months will overstate the back half and understate the front. For a small team of high earners, the distortion is visible.
The other is the phone call. Every year, somewhere in the organization, a well-paid employee notices their pay went up and assumes something broke. Answering that once, in writing, before September, costs a lot less than answering it thirty times.
The number employers forget to budget
Ask most payroll leads for the CPP maximum and you get $4,230.45. That is the base layer only, the whole answer before CPP2 existed, and the shape of the number still sitting in a lot of forecasting spreadsheets.
CPP2 did not replace a number anyone was already tracking. It added a second one, in a band most payroll reports never had a column for.
The gap is $416.00 per employee, per side. On a workforce of two hundred people earning above the second ceiling, that is $83,200 of employer contribution that was never in the model. It is not a large number per person. It is a large number in aggregate, and it arrives without an invoice.
That's not a rate problem. That's a version problem, and version problems live wherever the calculation is maintained by hand.
When do the maximums reset?
On the first pay of the calendar year. Not on a hire date, not on an anniversary.
This catches employers with mid-year hires. An employee who joined you in September and already hit both ceilings at a previous employer still has CPP and EI deducted on your payroll, because the Canada Revenue Agency does not net contributions across employers during the year. The employee recovers the overpayment when they file. You do not recover the employer portion.
It is worth telling that employee before they ask, because from where they sit it looks like a payroll error.
Where this sits in the payroll run
Every figure in the CPP and EI maximum for 2026 lands in one of five lines. Here they are together, employee side and employer side, because the two are not symmetrical.
| 2026 figure | Employee | Employer |
|---|---|---|
| CPP base, to $74,600 at 5.95% | $4,230.45 | $4,230.45 |
| CPP2, $74,600 to $85,000 at 4.00% | $416.00 | $416.00 |
| CPP total | $4,646.45 | $4,646.45 |
| EI, to $68,900 at 1.63% | $1,123.07 | $1,572.30 |
| EI, Quebec, at 1.30% | $895.70 | See QPIP schedule |
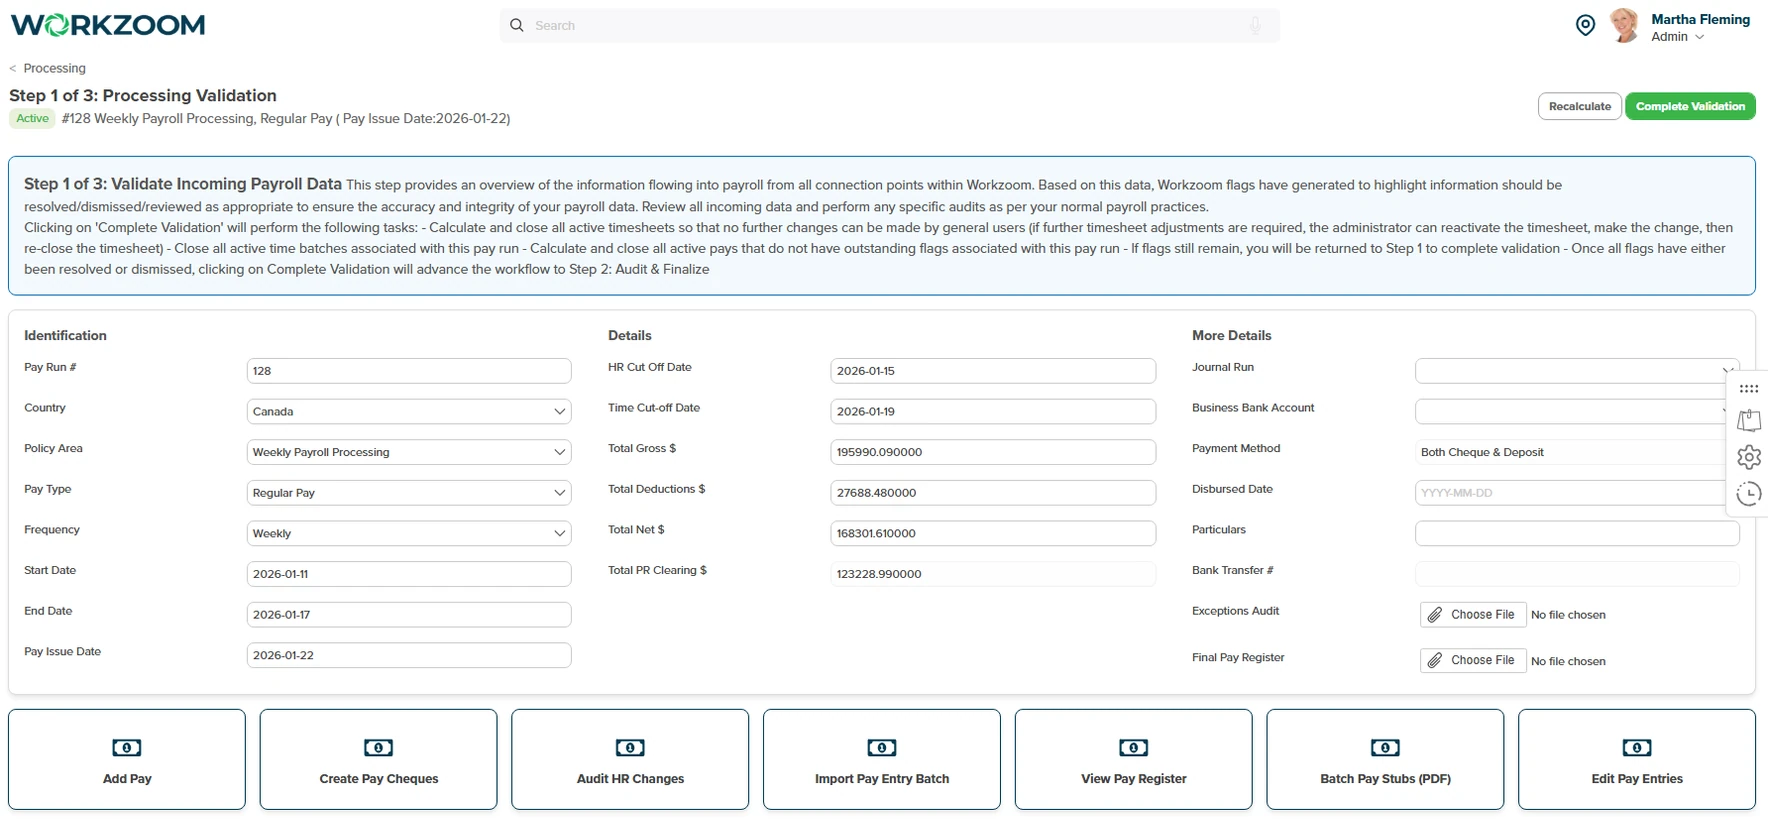
Public-sector employers run this across multiple pay groups at once. That is the setup at the County of Renfrew. Workzoom calculates both CPP layers and the EI employer multiplier on every Canadian pay run, and prepares the CRA remittance files. You submit them. We do not file with the government on your behalf, and any vendor who tells you they do is describing something other than what happens.
What we have not solved
From our 25 years of running Canadian payroll, the ceiling update has always been the same job: change two numbers before the first pay of the year, and leave every prior year's payslip exactly as it was.
No software knows next year's ceilings before the Canada Revenue Agency publishes them. What good payroll software does is make the update a configuration change rather than a hunt through formulas, and make last year's numbers still correct on last year's payslips.
That second part matters more than it sounds. Plenty of systems update a rate globally and quietly rewrite history, which is a problem the first time someone audits a prior year.
We are not going to pretend the annual update disappears. It gets smaller.
The version that is right in January
Statutory rates are not where anyone wants to spend judgment. They are published, they are unambiguous, and they should be settled before the first pay of the year rather than reconciled after the third.
If your CPP calculation still stops at $4,230.45, the number to fix is $416.00, and the place to fix it is wherever that formula lives.
Running Canadian payroll across provinces?
Workzoom handles both CPP layers, the EI employer multiplier, and Quebec's separate rates in the same pay run, and prepares your CRA files for submission. From $4 to $16 per employee per month, no setup fees, month to month.
Book a walkthroughSee Workzoom in 30 minutes.
Real product, real questions, no slides. Starts at $4 per employee per month, CAD or USD, with $0 setup fees.
What readers ask after this post on CPP and EI maximum 2026.
Our clients
The teams that run their people on Workzoom.
Workzoom handles HR, payroll, workforce, and talent on one employee record. Book a 30-minute walkthrough.