 Canada
 United States
 Bahamas
 Jamaica
 Trinidad & Tobago
 Antigua & Barbuda
 Barbados
 Anguilla
Canadian Payroll 2026: What Changes When Quebec Joins
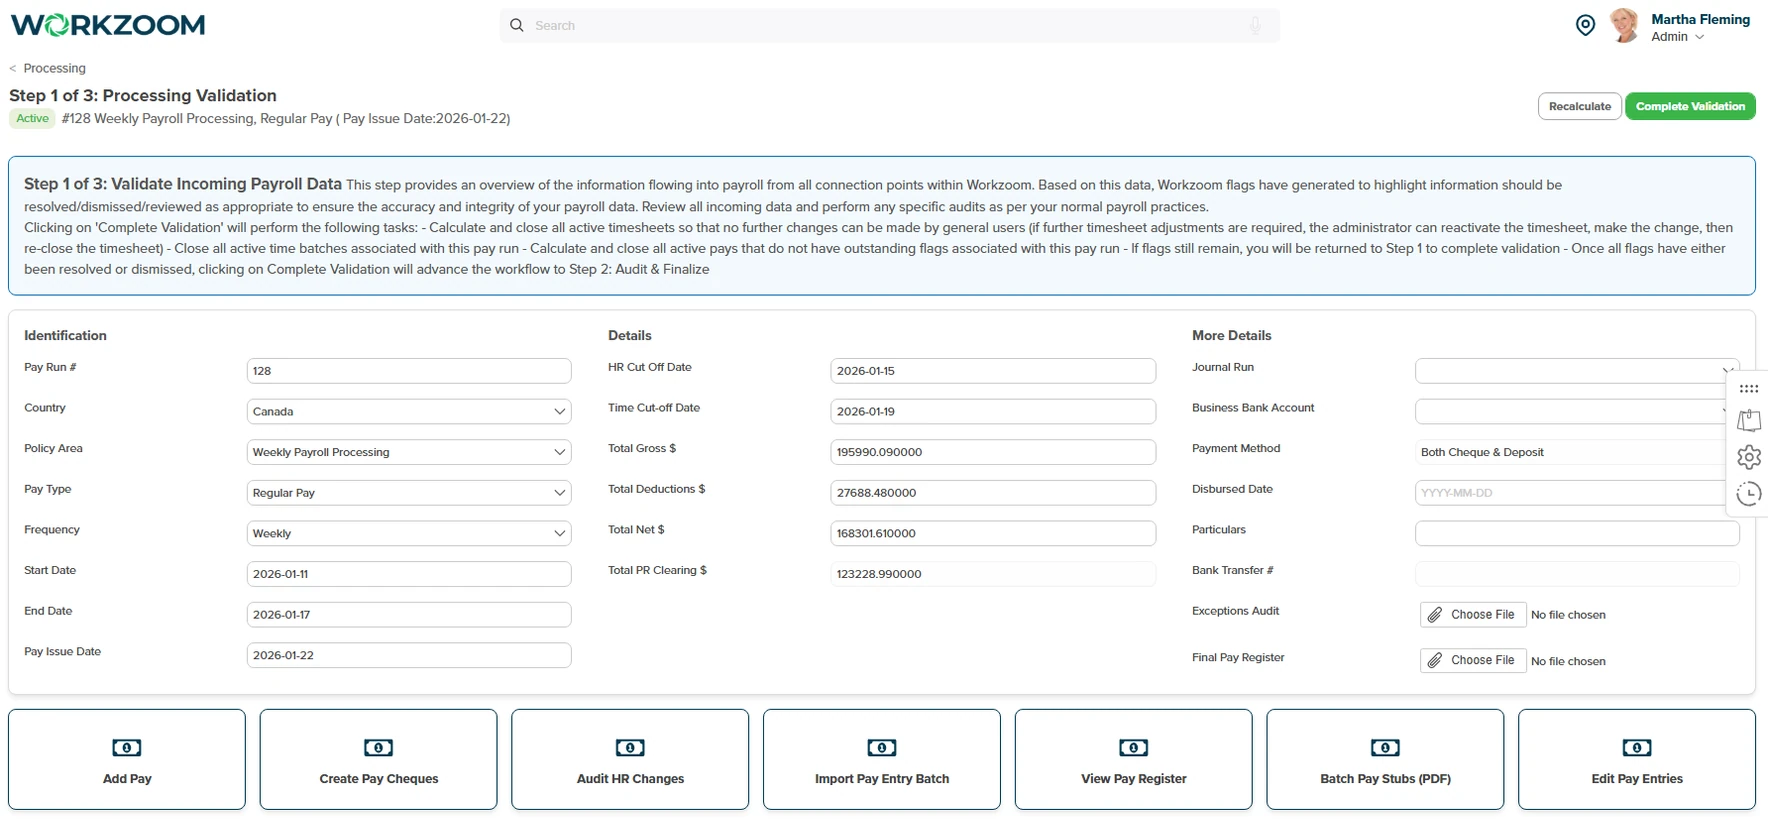
Most employers don't underestimate Canadian payroll. They underestimate how many separate systems it actually is. There is no country in the developed world where payroll is quite this layered. Canada asks employers to simultaneously manage a federal pension system with two separate ceilings, an employment insurance program that works differently in one province, a year-end filing regime that has its own province-specific parallel, and employment standards that change at every border. The pattern we see across our Canadian client base is consistent: the employers who get burned aren't careless. They're running fourteen layers in a tool built for one.
A company with 200 employees spread across Ontario, Alberta, and Quebec is genuinely running three different Canadian payroll systems on top of a shared federal framework. Get any one of the fourteen layers wrong and the CRA, Service Canada, or a provincial labour board will eventually let you know. That's not a discipline problem. That's an architecture problem.
This guide is the definitive overview of Canadian payroll for 2026. It covers every major obligation, links to the detailed post on each topic, and explains why the pieces connect the way they do. If you're new to Canadian payroll, start here. If you've been running payroll for years and things have gotten complicated, start here too.
- Canadian payroll runs on a federal framework plus thirteen provincial and territorial regimes that each set their own employment standards
- Mandatory deductions are CPP and CPP2, EI (with reduced Quebec rate), and federal plus provincial income tax. Employers match CPP and CPP2 and pay 1.4x the EI premium
- Quebec payroll combines QPP, QPIP and Quebec-tax obligations to Revenu Quebec with federal income tax and EI remittances to CRA. Apply the separate RL-1 and T4 reporting rules.
- ROE timing depends on filing method and pay frequency. CRA remittance timing depends on the assigned category, with lateness and conduct affecting penalties.
- Workzoom is Canadian-built, handles every province natively, and is $4 per employee per month per suite with no setup or implementation fees
Why Canadian Payroll Is Uniquely Complex
Most countries have one payroll system. Canada has fourteen: one federal framework and thirteen provincial and territorial regimes that sit on top of it. That dual structure is not an accident. Employment law is constitutionally provincial in Canada, which means the federal government sets the rules for pensions and employment insurance while every province sets the rules for how you actually manage employees.
What makes this genuinely hard is that the two layers don't always line up. Federal EI provides parental benefits, but provincial employment standards determine how long the job is protected during that leave. Federal payroll deductions are the same across every province except Quebec, which operates a parallel system for pensions, parental insurance, and income tax administration. And every province has its own overtime thresholds, statutory holiday counts, vacation minimums, and termination notice rules.
Add CPP2 (a second pension ceiling introduced in 2024 that many systems still don't handle correctly), the remote-work province-of-employment question, and growing pay equity obligations, and you have a compliance environment that is genuinely difficult to stay on top of manually.
The good news: every one of these obligations is predictable if you know the rules. This guide walks through each one. For the full HR and payroll guide for Canada, including employment standards and workforce management, we've covered everything in one place.
Source Deductions: The Foundation of Every Pay Run
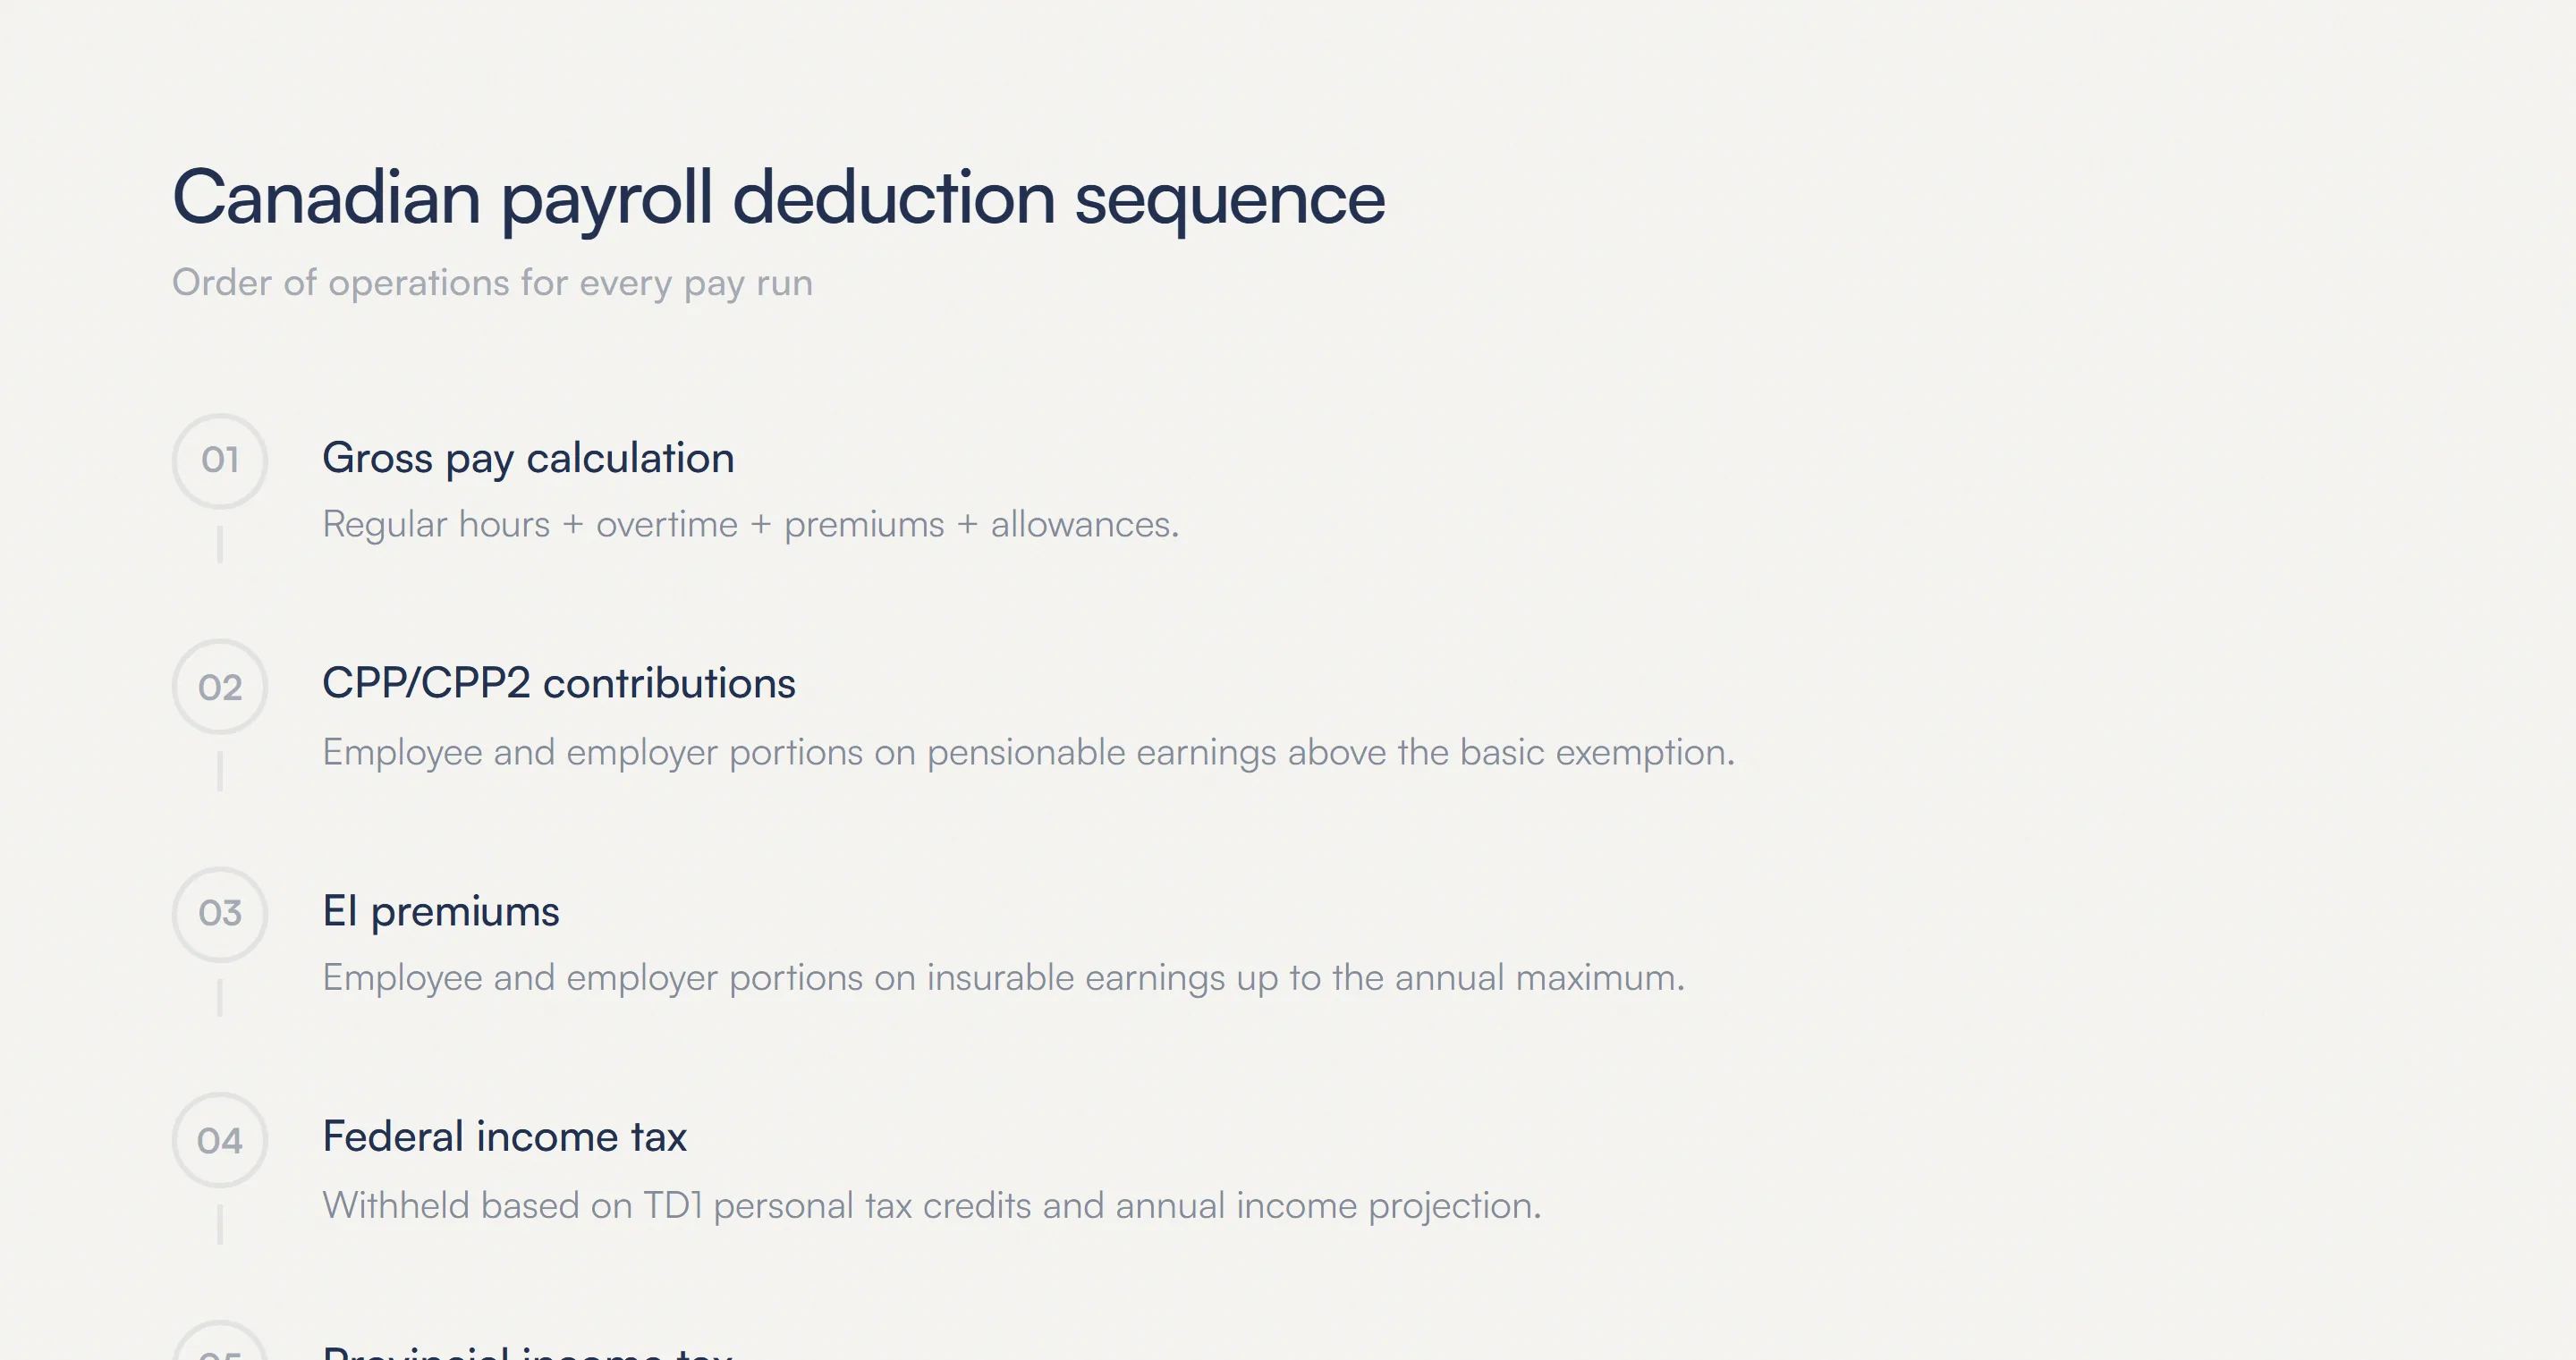
Every Canadian paycheque requires you to withhold three mandatory deductions before the employee sees a dollar: Canada Pension Plan contributions, Employment Insurance premiums, and income tax. Miss any of them and the liability lands on you, not the employee.
Canada Pension Plan (CPP and CPP2)
CPP applies to employees aged 18 to 69 earning above the $3,500 basic exemption. For 2026, the first ceiling sits at $74,600 with a contribution rate of 5.95% for both employee and employer. You match every dollar your employee contributes.
CPP2 is the piece that is still tripping up experienced teams. Introduced in 2024, it adds a second earnings ceiling at $85,000. Earnings between $74,600 and $85,000 attract an additional 4.00% from both the employee and employer. It is not a rate increase on regular CPP. It is a separate second-ceiling calculation. Systems that treat it as a blended rate produce wrong deductions for any employee earning between those two numbers.
Quebec employees contribute to the Quebec Pension Plan (QPP) at 6.30% instead of CPP. That is a completely separate calculation path, not a rate swap.
Employment Insurance
EI premiums apply to almost every employee in insurable employment. The 2026 numbers: employees pay 1.63% on insurable earnings up to $68,900. Employers pay 1.4 times the employee rate, which works out to 2.282%. Maximum annual employer EI premium per employee: $1,572.30.
Quebec employees pay a reduced EI rate (1.30%) because QPIP covers parental benefits in that province. This creates a separate calculation requirement for Quebec employees that cannot simply be applied by swapping a rate.
Federal and Provincial Income Tax
The full-year 2026 lowest federal rate is 14%, following the reduction that began in July 2025. Federal brackets now run from 14% on the first $58,523 up to 33% above $258,482. Provincial rates add another layer, ranging from roughly 4% (Nunavut's lowest bracket) to over 20% (Nova Scotia's highest).
Province of employment determines which provincial rate applies under CRA's employer-establishment test. For remote work, assess reasonable attachment to an establishment and use the paying-establishment fallback where applicable. The home address alone does not decide withholding.
For a thorough breakdown of every 2026 rate, threshold, and table, including the specific CPP2 calculation logic and the taxable benefit rules that most employers miss, see our guide to Canadian payroll deductions.
The total employer-side cost per employee earning $75,000 in Ontario is roughly $6,000 to $7,500 annually in CPP match, EI premiums, WSIB, and employer health tax, on top of salary. These costs are mandatory, they match your payroll size exactly, and they increase every January with CRA rate adjustments.
CRA Remittance: Deadlines That Change as You Grow
Withholding the right amounts is step one. Getting them to the CRA on time is step two, and step two has a trap built into it: your remittance frequency changes automatically as your company grows, and the CRA does not notify you when it happens.
Frequency is determined by your average monthly withholding amount (AMWA):
- Under $25,000 AMWA: Monthly, due by the 15th of the following month
- $25,000 to $99,999 AMWA: Twice monthly (accelerated threshold 1)
- Accelerated threshold 2: CRA assigns four monthly due periods ending on the 7th, 14th, 21st, and month-end
Late penalties start at 3% for amounts 1 to 3 days late and reach 10% for amounts more than 7 days late. The 20% rate applies only to qualifying second or subsequent assessments involving knowing or grossly negligent failures. CRA charges prescribed compound daily interest on overdue amounts.
The companies that get caught by this are almost always ones that grew. They were monthly remitters at 150 employees. They hired to 250. Their AMWA quietly crossed $25,000. Nobody updated the calendar. The full breakdown of frequencies, the specific dates, and the most common timing mistakes is in our CRA payroll remittance guide.
Year-End: T4 Slips and the February Deadline
Apply CRA’s T4 reporting conditions to each employee, including former staff. Quebec employers also produce RL-1 slips. Check each authority’s last-day-of-February deadline and weekend/public-holiday rollover rule. Every T4 must reconcile with your actual remittances for the year. If there's a discrepancy, the CRA will find it.
Common T4 errors include taxable benefits left out of Box 14 and incorrect province-of-employment codes. Determine income-tax, CPP/QPP, and EI/QPIP treatment separately for each benefit because taxable does not automatically mean pensionable and insurable.
Our T4 slips guide covers every box, the amendment process, and the specific taxable benefit rules that cause the most reconciliation failures.
Payroll calculated correctly, every pay run
Workzoom handles CPP, CPP2, EI, and federal/provincial tax across every Canadian jurisdiction. T4 generation, ROE filing, remittance tracking, statutory holiday pay. Built in Canada, for Canadian employers. $4/employee/month, no setup fees, no contracts.
Book a WalkthroughRecords of Employment: The Filing Nobody Gets Right
Issue an ROE when Service Canada’s interruption-of-earnings rules require one. An employer filing a Record of Employment electronically on a weekly, biweekly or semi-monthly payroll must issue it within 5 calendar days after the end of the pay period in which the employee's interruption of earnings occurs. On a monthly payroll, or a payroll with 13 pay periods a year, the deadline is the earlier of 5 calendar days after the end of that pay period or 15 calendar days after the first day of the interruption of earnings. An employer issuing a paper Record of Employment must issue it within 5 calendar days of the first day of the interruption of earnings, or of the day the employer becomes aware of the interruption, whichever applies.
The ROE reason code and required blocks must match the facts. Block 15A reports total insurable hours, 15B total insurable earnings, 15C earnings by pay period, and Block 17 separation payments. Service Canada administers ROE and EI benefit decisions.
The full walkthrough of every block, the reason codes, and the mistakes that generate the most Service Canada inquiries is in our Records of Employment guide.
Quebec Payroll: A System Within a System
Quebec does not simply use higher rates within the Canadian framework. It operates a parallel system that requires entirely separate calculations for every employee working in the province.
Instead of CPP, Quebec employees contribute to the Quebec Pension Plan (QPP) at 6.30%. Instead of federal parental EI benefits, Quebec has the Quebec Parental Insurance Plan (QPIP), which means Quebec employees pay a lower EI rate (1.30% vs 1.63%) but add QPIP contributions on top. Provincial income tax is administered by Revenu Quebec, not the CRA, which means Quebec employees file two separate tax returns and employers remit to two separate agencies. And at year-end, Quebec employers issue RL-1 slips in addition to T4s.
For an employer with employees in both Quebec and other provinces, you are genuinely running two parallel payroll systems. Not one system with Quebec adjustments. Two systems. The compliance obligations, the remittance authorities, and the year-end filings are all different. Our Quebec payroll guide covers the full scope of what's different and how to manage it without duplicating your entire payroll function.
Provincial Employment Standards: Overtime, Vacation, and Statutory Holidays
Once you've handled the federal deductions, you're working within provincial employment standards that govern how you actually manage people. These differ enough across provinces that what's compliant in Ontario is genuinely non-compliant in B.C.
Overtime
1.5x pay after 44 hours/week for most employees, weekly unless a contract or collective agreement or averaging agreement says otherwise, managers/supervisors excluded. Under the British Columbia Employment Standards Act, an employer must pay an employee who is not working under an averaging agreement overtime wages of 1.5 times the employee's regular wage for time worked over 8 hours in a day, double the regular wage for time worked over 12 hours in a day, and 1.5 times the regular wage for time worked over 40 hours in a week, counting only the first 8 hours worked in each day toward that weekly total. The Act's hours of work and overtime rules do not apply to a manager. Four shifts lasting exactly twelve hours each do not, by themselves, trigger BC daily double time. Assess the daily and weekly calculations without double-counting.
Statutory Holiday Pay
Statutory holiday counts range from 5 (some jurisdictions) to 10+ depending on the province. The eligibility rules differ too. Most provinces use an averaging formula to calculate holiday pay, but the look-back period and the definition of regular wages vary by jurisdiction. Our statutory holiday pay guide covers the province-by-province calculations and the averaging errors that show up most often on audits.
Vacation
Most provinces require 2 weeks of vacation entitlement after year one at a minimum accrual of 4% of gross wages. Saskatchewan is the outlier: 3 weeks from year one at 5.77%. For multi-province employers applying one vacation rate to everyone, you are either over-accruing in some provinces or under-entitling in Saskatchewan.
Severance and Termination Pay
Termination obligations in Canada combine two separate legal frameworks: statutory minimums under provincial employment standards, and common law reasonable notice as established by courts. The gap between them is where most wrongful dismissal exposure lives.
Under Ontario's Employment Standards Act, an employee continuously employed for at least three months whose employment is terminated individually, and who is not disqualified by the Act's exemptions, is entitled to notice of termination, or termination pay instead of notice, of one week for less than one year of service, two weeks for one to three years, three weeks for three to four years, four weeks for four to five years, five weeks for five to six years, six weeks for six to seven years, seven weeks for seven to eight years, and eight weeks for eight or more years. Under Ontario's Employment Standards Act, an employee whose employment is severed after five or more years of service is entitled to severance pay equal to regular wages for a regular work week multiplied by the sum of completed years of employment plus completed months divided by 12 for a year that is not completed, to a maximum of 26 weeks, if the employer has a global payroll of at least $2.5 million or severed 50 or more employees in a six-month period because all or part of the business permanently closed. Severance pay is separate from and additional to termination pay. Determine the applicable employment regime before using an Ontario calculation.
Additional notice or compensation may arise under the applicable contract and employment regime. Statutory pay is not automatically added on top of a separate common-law award; amounts can overlap. Quebec civil law, federal protections and collective agreements require their own analysis. See the severance guide for jurisdiction-specific distinctions.
Parental and Maternity Leave
Federal EI provides maternity benefits (15 weeks) and parental benefits (standard 40 weeks or extended 69 weeks at a reduced rate). But the EI benefit period and the job-protected leave period are set by different governments and don't always align.
In Ontario, birth parents can take up to 61 weeks of job-protected parental leave. In B.C., it's 62 weeks. An employee can be on EI benefits for one duration and on job-protected leave for a different duration, and your obligation to hold their position extends through the longer of the two. Getting this wrong, not holding the job long enough, is one of the most common termination-related claims.
Quebec operates QPIP, its own parental leave benefit, which means Quebec employees access parental benefits through a different program with different duration and rate rules. Our parental leave and payroll guide covers the employer obligations during leave, the interaction between EI and job protection, and how top-up policies work.
Pay Equity: What's Changing
Pay equity legislation is expanding beyond the public sector. The federal Pay Equity Act (2021) requires all federally regulated employers with 10 or more employees to develop and post a pay equity plan. Ontario's Pay Equity Act covers both public and private sector employers. Quebec has had proactive pay equity since 1996. Several other provinces are actively moving toward similar requirements.
The distinction between proactive and complaint-based pay equity matters. Under proactive models, the employer must audit compensation and fix gaps without waiting for a complaint. The burden is on you. Employers who are still operating on a complaint-first model are running a compliance gap that is being legislated shut across the country.
Reporting deadlines are also tightening. Federally regulated employers who completed their initial pay equity plans in 2024 or 2025 are now approaching their first posting and update cycles. Our pay equity legislation guide covers the current obligations by jurisdiction, the reporting timelines, and the penalties for non-compliance.
Pay equity is no longer a public sector or large employer concern. If you are federally regulated with 10+ employees, you have a legal obligation to develop, post, and maintain a pay equity plan. Ontario's private sector obligations apply at the 10-employee mark as well. The question is not whether you'll need to comply. It's whether you'll have the data to do it when the deadline arrives.
Is Your Payroll System Actually Doing Its Job?
A lot of payroll problems in Canada don't look like problems until they become CRA notices. The system runs. Employees get paid. Numbers come out. But CPP2 is misconfigured for a particular earnings band. Provincial tax is being applied with a stale bracket. Remittance frequency changed and no one updated the calendar.
The signs of a payroll system that's failing are usually quiet: manual overrides that keep multiplying, reconciliation errors that get fixed by hand every period, T4 amendments filed two years in a row, a payroll admin who is the only person who knows how the system actually works. Our post on the signs your payroll system is failing covers the most common symptoms and what they usually mean structurally.
If you've reached the point where the system is clearly not keeping up, the process of actually switching providers is its own challenge. Most employers underestimate the data migration complexity and overestimate the disruption. Our guide to switching payroll providers walks through the process, the questions to ask prospective vendors, and what a good implementation actually looks like.
Canadian payroll built for Canadian compliance
Workzoom is 100% Canadian-owned (Nortek Solutions Inc., Toronto), founded in 2000, and built specifically for Canadian payroll complexity. CPP2 handled natively. Quebec parallel system supported. Multi-province tax calculations. T4 generation. ROE filing. Provincial statutory holidays and overtime by jurisdiction. $4/employee/month per suite, no setup fees, no implementation fees, no contracts.
Book a WalkthroughConnecting Payroll to the Rest of Your HR
Payroll does not exist in isolation. Every HR event creates a payroll downstream effect. A promotion changes the deduction calculations. A leave of absence changes the ROE obligation and the benefit continuation rules. A province change changes the tax withholding, the overtime rules, and the statutory holiday calendar. A new hire triggers TD1 collection, EI registration, and CPP enrollment.
When HR and payroll live in separate systems, these updates rely on someone manually carrying information from one system to the other. The lag between when something changes in HR and when it's reflected in payroll is a compliance gap. It's also a data integrity problem, because by the time it surfaces, you may have run several incorrect pay periods.
The case for connecting HR and payroll in one system isn't about convenience. In a compliance environment as layered as Canada's, a single record that flows automatically from hire through every change to termination is the only architecture that actually keeps up. Our full overview of the HR compliance obligations that run alongside payroll is in the HR compliance checklist for 2026.
More from the Canadian Payroll Series
This guide is the hub for Workzoom's complete Canadian Payroll series. Each post below covers a specific topic in depth, with the 2026 rates, rules, and compliance requirements fully updated.
- Canadian Payroll Deductions: A Complete 2026 Guide. CPP, CPP2, EI, federal and provincial income tax, taxable benefits, and the five mistakes that cost the most
- CRA Payroll Remittance: Deadlines, Frequencies, and Penalties (2026). every threshold, every deadline, and how to avoid the growing-company trap
- T4 Slips in Canada: Employer Guide (2026). every box, taxable benefit inclusions, the amendment process, and reconciliation errors
- Records of Employment in Canada: Complete Employer Guide (2026). reason codes, insurable earnings, insurable hours, filing-method and pay-frequency deadlines
- Statutory Holiday Pay in Canada: What Employers Actually Owe (2026). province-by-province calculations and the averaging formula mistakes
- Quebec Payroll Compliance: The Complete Guide for Employers. QPP, QPIP, Revenu Quebec, RL-1 slips, and the full parallel system explained
- Severance Pay in Canada: What Employers Owe (2026). statutory minimums by province, common law notice, Bardal factors, total liability calculation
- Parental Leave and Payroll in Canada: Employer Guide (2026). EI benefits, job protection periods, QPIP, and top-up policies
- Pay Equity Legislation in Canada: What Employers Need to Know. proactive vs complaint-based models, federal and provincial obligations, reporting deadlines
- 7 Signs Your Payroll System Is Failing. quiet symptoms of a system that's creating compliance risk
- How to Switch Payroll Providers (Without the Usual Pain). data migration, questions to ask vendors, what good implementation looks like
- Why HR and Payroll Belong in One System. the compliance case for a single connected record
- Full HR and Payroll Guide for Canada. employment standards, workforce management, leave entitlements, and compliance calendar in one place
- HR Compliance Checklist for Canadian Employers (2026). every deadline and obligation organized by month
- Late remitting/Failure to remit claim checked Sep 4, 2026
- Employers: How to complete the record of employment (ROE) form claim checked Sep 4, 2026
- Your guide to the Employment Standards Act: Overtime pay claim checked Sep 4, 2026
- Employment Standards Act, RSBC 1996, c 113, ss 35 and 40, and Employment Standards Regulation, BC Reg 396/95, s 34 (f) claim checked Sep 4, 2026 also Employment Standards Regulation, BC Reg 396/95, s 34 (f)
- Your guide to the Employment Standards Act: Termination of employment claim checked Sep 4, 2026
- Your guide to the Employment Standards Act: Severance pay claim checked Sep 4, 2026
See Workzoom in 30 minutes.
Real product, real questions, no slides. Starts at $4 per employee per month, CAD or USD, with $0 setup fees.
What readers ask after this post on canadian payroll.
Our clients
The teams that run their people on Workzoom.
Workzoom handles HR, payroll, workforce, and talent on one employee record. Book a 30-minute walkthrough.